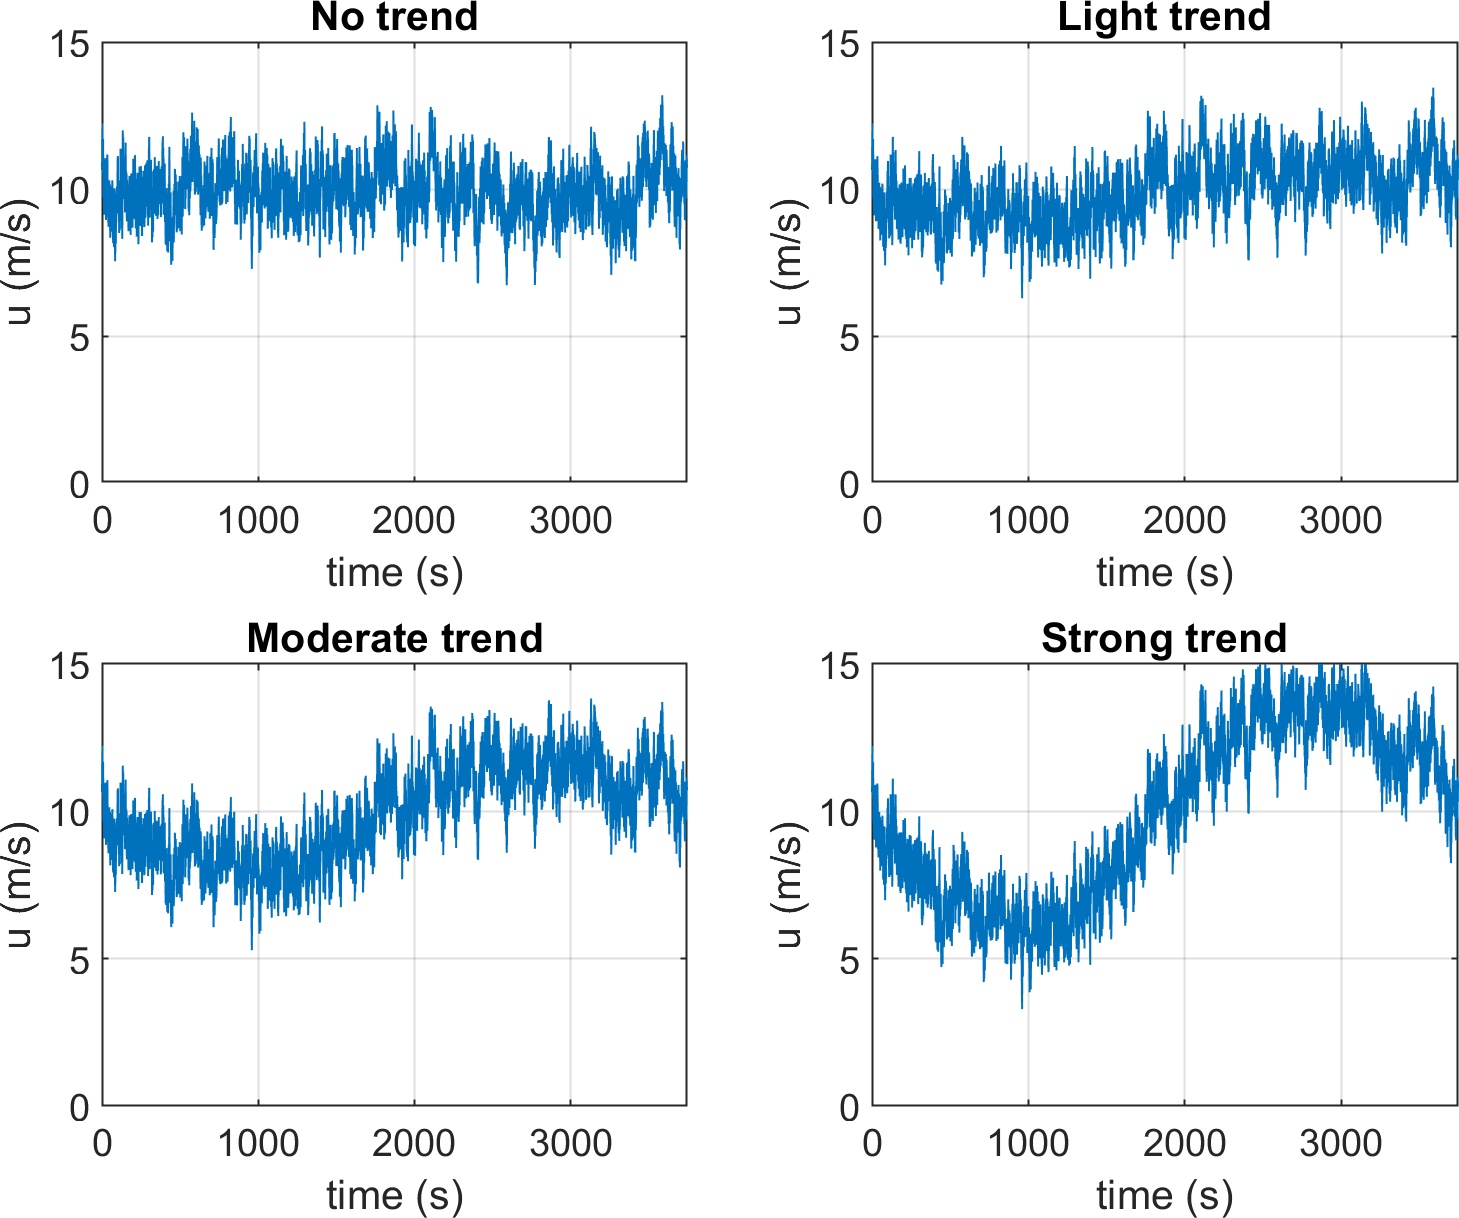
Stationarity test
The stationarity of a time series is evaluated by using the reverse arrangement test or moving-window functions

You are now following this Submission
- You will see updates in your followed content feed
- You may receive emails, depending on your communication preferences
Cite As
E. Cheynet. ECheynet/StationaryTests: Sationarity Tests for Random Process. Zenodo, 2020, doi:10.5281/ZENODO.3891111.
Cheynet, Etienne, et al. “Flow Distortion Recorded by Sonic Anemometers on a Long-Span Bridge: Towards a Better Modelling of the Dynamic Wind Load in Full-Scale.” Journal of Sound and Vibration, vol. 450, Elsevier BV, June 2019, pp. 214–30, doi:10.1016/j.jsv.2019.03.013.
Acknowledgements
Inspired by: One-point random process generation, Averaging noisy data into bins
General Information
- Version 1.3.0 (108 KB)
-
 View License on GitHub
MATLAB Release Compatibility
- Compatible with R2016a and later releases
Platform Compatibility
- Windows
- macOS
- Linux
| Version | Published | Release Notes | Action |
|---|---|---|---|
| 1.3.0 | See release notes for this release on GitHub: https://github.com/ECheynet/stationaryTests/releases/tag/v1.3 |
||
| 1.2.1 | See release notes for this release on GitHub: https://github.com/ECheynet/stationaryTests/releases/tag/v1.2.1 |
||
| 1.2.0 | See release notes for this release on GitHub: https://github.com/ECheynet/stationaryTests/releases/tag/v1.2 |
||
| 1.1.0 | Title |
||
| 1.0.0 | -typo |

